Entitlement to a partial tax credit under Article 73 of the Value Added Tax Act (VAT Act)
By Гергана ПетроваPublished On: 31/10/2023Last Updated: 31/10/2023
A person registered under the Value Added Tax Act may carry out both taxable supplies and supplies for which there is no right to a tax credit.
The right to deduct input tax under the VAT Act arises and is exercised in accordance with the general rules set out in Article 69, subject to the restrictions in Article 70 and the conditions in Article 71 of the Act. Pursuant to Article 69(1) of the VAT Act, a registered person is entitled to deduct the tax charged on goods or services which the supplier — a person registered under this Act — has supplied or is due to supply to them, where the goods and services are used for the purposes of the taxable supplies carried out by them.
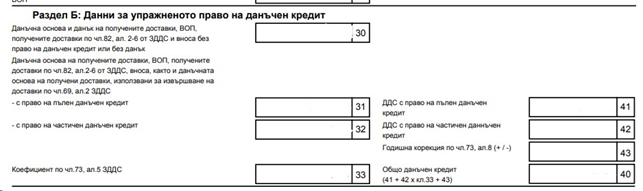
The text of Article 73( 1 of the VAT Act states that a registered person is entitled to a partial tax credit in respect of the tax on goods or services which are used both for the supply of goods or services in respect of which the person is entitled to a tax credit, and for supplies or activities in respect of which the person has no such right.
To determine the amount of the partial tax credit, the law provides for a specific procedure in Article 73(2) of the VAT Act. Under the Act, the amount of the tax credit must be multiplied by a coefficient calculated to two decimal places, obtained as the ratio between the turnover relating to the supplies in respect of which the person is entitled to a tax credit and the turnover relating to all supplies and activities carried out by the person.
In accordance with the provisions of Article 73(3) of the VAT Act, the turnover relating to supplies in respect of which the person is entitled to a tax credit (tax bases which are included in the numerator when calculating the coefficient) comprises:
the tax bases of the taxable supplies made by the person;
the tax bases of the payments received by the person, in respect of which the tax became chargeable before the occurrence of the taxable event relating to a taxable supply;
the tax bases of the supplies made by the person where the place of supply is outside the country, treated as taxable in accordance with Article 69(2) of the Act, with the exception of supplies with a place of supply outside the country, carried out by a permanent establishment of the person outside the country;
the tax bases of the payments received by the person prior to the supply of goods or services referred to in the previous point;
the taxable amount of supplies of goods or services in respect of which the right to deduct input tax has not been exercised pursuant to Article 70(1)(3)-(5) of the Act.
The turnover relating to all of the person’s supplies and activities (which is included in the denominator when calculating the ratio) is determined in accordance with Article 73(4) of the Value Added Tax Act and includes:
turnover under Article 73(3) of the Value Added Tax Act;
the tax bases of supplies made by the person where the place of supply is outside the country’s territory, which are not treated as taxable within the meaning of Article 69(2) of the Act, with the exception of supplies carried out by the person’s fixed establishment outside the country;
the taxable amounts of the exempt supplies made, with the exception of those referred to in Article 50(1)(2) of the VAT Act;
the value of supplies and activities falling outside the scope of the person’s economic activity, with the exception of those for which no tax credit is allowed pursuant to Articles 71a and 71b of the Value Added Tax Act;
the tax bases of the payments received by the person prior to the performance of the supplies and activities referred to in the points listed above;
the amount of subsidies received, other than those included in the tax base.
At the same time, Article 64(1) and (2) of the Regulations for the Implementation of the Value Added Tax Act (RIVA) specify cases of supplies which are not included in the turnover referred to in Article 73(3) and (4) of the Act. The following supplies are not included:
property as a result of a request or act by a state or local authority, or on the basis of a law, where no compensation is provided;
fixed assets used by the taxpayer in the course of their independent economic activity;
property and financial services of an incidental nature;
interest received on current and deposit accounts in certain cases.
The VAT Act and the VAT Implementation Regulations do not provide any clarification regarding the term ‘incidental’. It can be inferred from EU Directives and case law that ‘incidental’ refers to supplies of secondary importance or of an exceptional nature in relation to the company’s total turnover, and such supplies do not form part of the taxable person’s normal business activities.
An economic activity is classified as ‘ancillary’ provided that it does not constitute a direct, permanent and necessary extension of the enterprise’s taxable activity and does not involve the significant use of goods or services on which VAT is due. Turnover from transactions of an ancillary (incidental) nature should not be included when determining turnover under Article 73, paragraphs 3 and 4 of the VAT Act, where the supplies are of secondary importance or of an exceptional nature in relation to the total turnover realised by the enterprise and these supplies do not correspond to the taxable person’s usual business activity.
The coefficient is calculated on the basis of the turnover for the entire preceding calendar year, and where no such turnover is available for the preceding calendar year, on the basis of the turnover for the tax period during which the right to claim a tax credit arises.
The amount of the partial tax credit is recalculated in the final tax period of the current calendar year on the basis of the figures for the current calendar year. The difference resulting from the recalculation is included as an adjustment (increase or decrease) to the amount of the tax credit in the tax return for the final tax period (month 12 of the current year).
In cases of deregistration, the amount of the partial tax credit is recalculated at the end of the last tax period on the basis of the figures for the part of the current calendar year during which the person was registered. The difference resulting from the recalculation is included as an adjustment (increase or decrease) to the amount of the tax credit in the tax return for the last tax period.
EXAMPLE:
In 2021, the company carried out only taxable supplies and did not calculate the coefficient under Article 73. It claimed the full tax credit.
In 2022, the figures for deliveries made by the company were as follows:
tax period
VAT on taxable supplies made, BGN
Taxable value of exempt supplies made, BGN
Coefficient under Article 73
Jan 2022
1000
0
–
Feb 2022
5,000
0
–
March 2022
10,000
0
–
Apr 2022
20,000
0
–
May 2022
25,000
5,000
0.833333
In May 2022, for the first time, the company carried out not only taxable supplies with a taxable amount of 25,000.00 BGN but also exempt supplies with a taxable amount of 5,000.00 BGN. It must calculate the coefficient under Article 73 on the basis of the turnover for this tax period.
Coeff. = Total regional deliveries completed / (Total regional deliveries completed + Total inter-regional deliveries completed)
Coeff. = 25,000 / (25,000 + 5,000) = 0.8333333
In accordance with Article 64(3) of the VAT Implementation Regulations, the coefficient is calculated by rounding to the second decimal place up to the next higher number.
Coeff. = 0.84
The coefficient calculated in this way applies to all tax periods up to and including December 2022. The coefficient is recalculated in the final tax period of 2022 on the basis of the figures for the calendar year. The difference resulting from the recalculation is included as an adjustment (increase or decrease) to the amount of the tax credit in the tax return for the final tax period, December 2022.
tax period
VAT on taxable supplies made, BGN
Taxable value of exempt supplies made, BGN
Coefficient under Article 73
Taxable value of supplies received, BGN
VAT on supplies received, BGN
Right to a tax credit, BGN
Jan 2022
1000
0
–
1,000
200
200
Feb 2022
5,000
0
–
1,000
200
200
March 2022
10,000
0
–
0
0
0
April 2022
20,000
0
–
10,000
2,000
2,000
May 2022
25,000
5,000
0.840000
10,000
2,000
1,680
June 2022
20,000
0
0.84
10,000
2,000
1,680
July 2022
10,000
0
0.84
5,000
1,000
840
August 2022
10,000
5,000
0.84
2,000
400
336
September 2022
30,000
10,000
0.84
25,000
5,000
4,200
Oct 2022
25,000
2,000
0.84
10,000
2,000
1,680
Nov 2022
25,000
0
0.84
10,000
2,000
1,680
Dec 2022
20,000
0
0.84
10,000
2,000
1,680
Total 2022
201,000
22,000
0.901345
94,000
18,800
16,176
0.91
18,800
17,108
difference, BGN
932
Based on calculations for May 2022 Coefficient = 0.84; the company utilised a partial tax credit for the period May 2022 – December 2022 amounting to 16,176.00 BGN.
Based on the data for the whole of 2022, the coefficient has been calculated as 0.91
As a result of the recalculation, a difference of +932.00 BGN arises, which should be included as an annual adjustment (in this case, an increase) to the amount of the tax credit in the tax return for December 2022.
The coefficient of 0.91 is used throughout 2023 and is recalculated in December 2023 on the basis of the data for 2023.
We are an outsourcing company with a focus on new technologies, digitization of documents, optimization of work processes, building and management of teams.
This is how we achieve flexible conditions and comfortable service for the customer in a time of digital transformation of business processes all over the world. Every month we work with over 400 Bulgarian and international businesses thanks to our team of 70+ highly qualified specialists in the field of accounting and business process administration. We build and manage accounting and back office teams for businesses based outside of Bulgaria and execute processes entirely according to the client’s order. We strive to always give more.
We serve entirely online. We are here to be an integral part of our clients’ businesses and contribute to their success through our work!